Key Takeaways
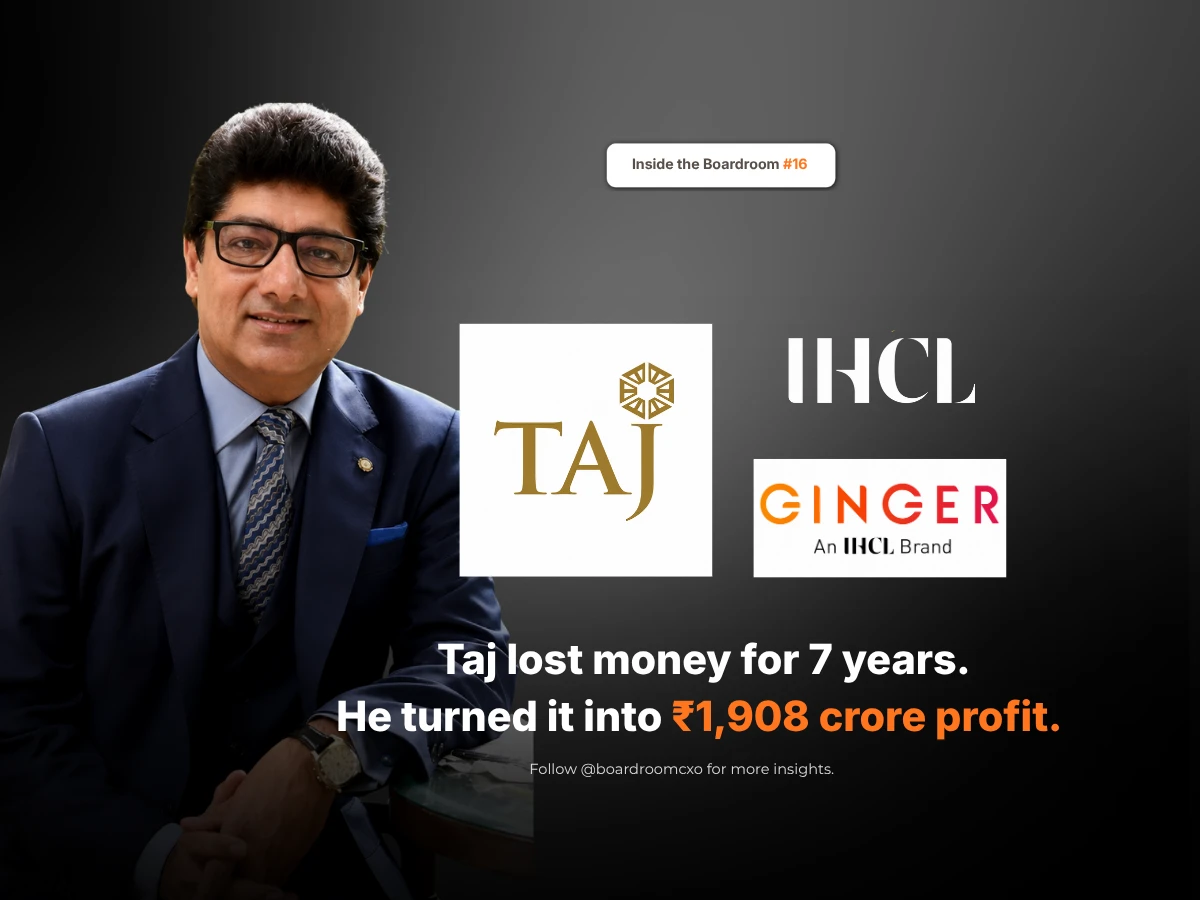
- Puneet Chhatwal took over IHCL on 6 November 2017 after seven straight years of losses, and by FY26 profit after tax reached ₹2,084 crore.
- During Covid, Chhatwal raised ₹4,000 crore and signed new hotels as management contracts, letting owners keep the building while IHCL ran it for a fee.
- Strong brands are rarely rescued by spending more, so boards should ask whether a turnaround candidate would fix the business model or just the balance sheet.
On 6 November 2017, a man who had spent close to three decades building hotels outside India came home to run the Taj. Almost nobody knew what he was walking into.
The Taj was one of the most loved brands in the country, and it had been losing money for seven straight years.
Who Is Puneet Chhatwal?
Puneet Chhatwal had been chief executive of Steigenberger Hotels in Frankfurt before taking over as managing director and CEO of the Indian Hotels Company Limited (IHCL). The consolidated net loss he inherited was ₹63 crore. Net debt stood at ₹3,151 crore. The company owned or leased most of its hotels, so every new hotel needed a big cheque before it earned a single rupee. His predecessor had resigned. The Taj name alone brought in 63% of enterprise revenue, around ₹4,500 crore, and the group's other brands were doing very little.
What He Did When Covid Hit
Then came Covid. In early 2020, travel stopped and hotels across the world shut their doors. IHCL lost ₹796 crore in the year to March 2021. Most leaders would have cut everything and waited for travel to come back. He did not.
He raised ₹4,000 crore while the recovery was still uncertain, half through a rights issue and half through a share sale to institutions. He kept signing new hotels, a record number in India for two years running, but signed them light, letting the owner keep the building while IHCL ran it for a fee, which is how you grow without buying anything.
He took Ginger, a budget brand, and rebuilt it as lean luxury. He launched Qmin during the pandemic to sell Taj food to people who could not leave home.
By FY26, profit after tax had crossed ₹2,000 crore for the first time, at ₹2,084 crore, on revenue of ₹9,971 crore. In the quarter to June 2026, IHCL reported its seventeenth record quarter in a row, with 645 hotels in its portfolio and ₹4,439 crore of gross cash. The share of hotels the company owns or leases has fallen steadily as growth moved to management contracts. He grew the Taj by owning less of it.
The Boardroom Lesson Most Turnaround Stories Miss
Most coverage of this story credits the recovery to Covid ending and travel demand returning. What gets skipped is that Chhatwal raised his largest capital round and made his biggest structural bet, the shift to management contracts, while the outcome was still completely unknown. The rights issue closed in December 2021 and the share sale in March 2022, with no certainty yet that travel would fully recover.
The strongest brands are rarely rescued by spending more. They are rescued by someone willing to change what the business is.
A hospitality group that had spent decades growing by building and owning hotels had to become one that grew by managing other people's buildings. That is not a cost-cutting fix. It is a change to the underlying business model, made under maximum uncertainty rather than after the answer was clear.
Common Mistakes Boards Make When Hiring a Turnaround CEO for a Legacy Brand
Boards evaluating a leader to fix a loved but financially struggling legacy brand tend to make the same three errors.
They confuse brand strength with financial health. Taj's emotional equity as a brand was never in question. Its seven straight years of losses had nothing to do with brand perception and everything to do with a capital-heavy ownership model. Boards should separate the two diagnoses before hiring for a fix.
They expect a turnaround to wait for stability. Chhatwal's largest capital raise and his structural pivot to asset-light growth both happened during the most uncertain period the global hospitality industry had faced in decades. Waiting for calmer conditions would have meant losing years of ground to competitors making the same shift.
They underweight brand-architecture fixes below the flagship. Ginger's repositioning from budget to lean luxury, and the Qmin launch, were smaller moves than the core Taj turnaround, but they addressed a real gap: a group whose non-flagship brands contributed almost nothing to revenue.
A Framework for Evaluating This Kind of Turnaround
When we brief boards on a CXO search involving a legacy hospitality, real estate, or asset-heavy consumer brand in financial distress, we push for three specific checks.
- Ask whether the candidate would fix the model or just the balance sheet. A leader who can only propose cost cuts and debt restructuring is treating the symptom. Chhatwal's actual fix was structural: changing how new growth gets funded, not just paying down what was already owed.
- Test their appetite for raising capital at the worst possible moment. The ₹4,000 crore raise happened mid-pandemic, when the outcome was maximally uncertain. Ask candidates directly how they would decide when to move on a major capital decision versus wait for more clarity.
- Look at what happens to the brands below the flagship. A group's secondary brands are often neglected during a crisis focused on the marquee name. Chhatwal's parallel work on Ginger and Qmin signals a leader managing the full portfolio, not just the headline asset.
Why This Belongs in the Boardroom, Not Just the Business Pages
This sits alongside the same insider-versus-outsider pattern we examined in Sudhir Sitapati's move from HUL to Godrej Consumer: a leader stepping into a smaller or more troubled mandate, using judgment built elsewhere to fix a problem the prior team could not. Chhatwal's version came from outside India entirely, built at a foreign hotel chain, applied to India's most storied hospitality brand at its lowest financial point in years.
The market does not reward the leader who spends the most to prop up a struggling brand. It rewards boards that can tell the difference between a turnaround built on more capital and one built on a genuinely different business model.
Sources
- IHCL, IHCL Announces Financial Results For Q1 FY 2027, July 2026
- IHCL, IHCL Announces Financial Results For Q4 And Full Year FY 2025-26, May 2026
- Forbes India, How Puneet Chhatwal has turned around the 120-year-old IHCL, March 2025
- Business Standard, Indian Hotels re-appoints Puneet Chhatwal as MD & CEO for 5 yrs from Nov 6, May 2022
- Business Standard, Indian Hotels turns in Rs 72 cr profit in Q4 against a loss last year, April 2022
- Mint, Indian Hotels' MD and CEO Rakesh Sarna resigns, May 2017
Related Reading
Sudhir Sitapati: Why He Left HUL's Safest Seat for Godrej
Read → R · 02 Founder Leadership · September 2026Anish Shah: The Outsider Who Fixed Mahindra's ₹5,200 Crore Problem
Read → R · 03 Founder Leadership · August 2026Everyone Said Royal Enfield Was Finished. Siddhartha Lal Asked for Two Years.
Read →Turning around a legacy brand and need leadership that has changed a business model under pressure?
We screen for candidates who can fix the structure of a business, not just its balance sheet. Brief us on your next CXO mandate and we will tell you what the market actually has to offer.
Brief Us on a Mandate See all Finance & CFO roles we fill →