Key Takeaways
- M P Ahammed opened a jewellery shop in Kozhikode in 1993, and as of October 2026 Malabar Gold & Diamonds runs more than 445 showrooms across 14 countries.
- Instead of waiting or borrowing, Ahammed sold debentures to investors, many working in the Gulf, with interest capped at 15% and conversion into shares once profitable.
- Because customers lend against who you are, boards should ask what trust a founder built before the business needed it.
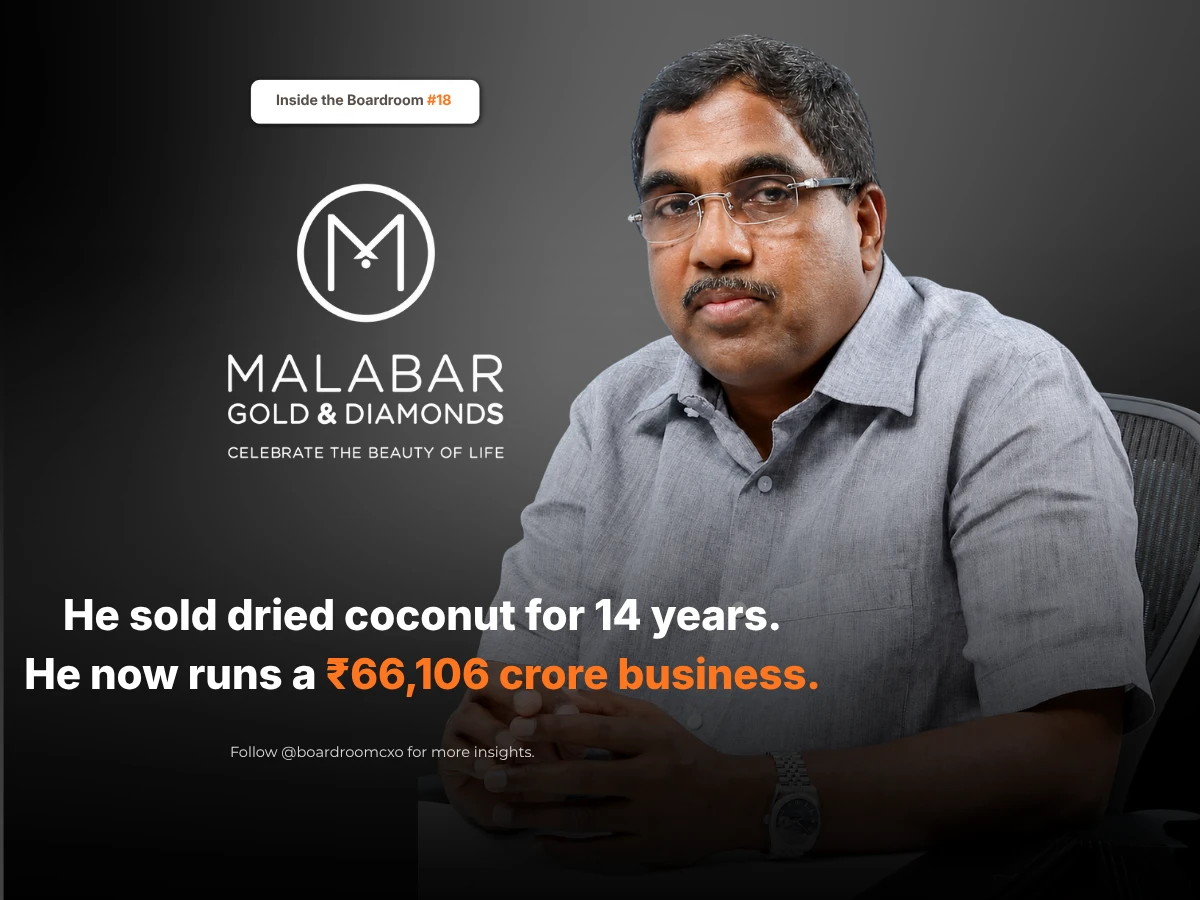
In 1993, a man who sold dried coconut in Kozhikode decided to sell gold. He was 36. He had finished school at Class 12.
M P Ahammed had spent twelve years selling dried coconut and spices to shopkeepers across Kerala, and had worked out it would never get big. He was looking for something that would. "My friend who was based in Mumbai told me gold prices will increase," he says.
Who Is M P Ahammed?
M P Ahammed is the founder and chairman of Malabar Gold & Diamonds, today India's largest jeweller by revenue. He could see why gold made sense in 1993. The rupee had fallen from ₹17.5 to the dollar in 1990 to ₹30 by 1993, so the money Kerala families were sent from the Gulf was suddenly worth far more. Gold was trading around ₹400 a gram.
He took a room of about 200 square feet on the first floor of a building and opened a jewellery shop.
The Financing Problem Every Jeweller Has
Customers came. But a jewellery shop is only as big as the gold sitting inside it, and every new store meant buying crores of stock before selling a single piece. He had nothing left to buy it with.
Most people in that position wait, or borrow at whatever rate they can get. He did not. He sold debentures instead, to investors, many of them working in the Gulf, with interest capped at 15% and the right to convert into shares once the business turned a profit. People who trusted him were paying for his next shop.
By 2008 it had 20 stores and had opened its first in the UAE. The 300th came in Dallas, in the United States, in 2023. Malabar Gold & Diamonds runs more than 445 showrooms across 14 countries as of October 2026. Revenue for the year to March 2026 was about ₹96,100 crore on provisional figures, up from ₹66,106 crore the year before. Deloitte's Global Powers of Luxury Goods 2023 list ranked it 19th in the world. Five percent of the profit goes to charity every year.
The Boardroom Lesson Most Founder Stories Miss
Most coverage of this story treats the debenture scheme as a clever workaround, a way around the banks. What gets skipped is what it actually required: enough trust with his own customer base that Gulf workers would hand over years of savings to a first-generation jeweller.
A bank lends against what you own. Customers lend against who you are.
That is a much harder thing to build than a credit history. A bank evaluates collateral. A customer base evaluates a track record of keeping its word, transaction by transaction, over years. Ahammed had spent twelve years building exactly that reputation in a different business before he ever needed it in this one.
Common Mistakes Boards Make When Evaluating Founder-Led Growth
Boards and investors evaluating a founder who scaled without conventional financing tend to make the same three errors.
They read unconventional financing as a sign of weak fundamentals. A founder who raises money outside the banks is not automatically a founder with a bad business. Ahammed had finished school at Class 12 and had never run a jewellery shop, yet the model held up across 445 stores.
They underweight the trust infrastructure a founder builds outside the business itself. The debenture scheme worked because of relationships built over a prior, unrelated twelve-year career. That kind of community trust rarely shows up on a balance sheet, but it is often the actual asset that made the growth possible.
They assume informal funding cannot scale. Malabar's debenture model scaled from a single Kozhikode shop to 445 stores across 14 countries. The structure that starts as an informal workaround can become a genuine, repeatable financing mechanism if the founder treats it with the same discipline as institutional capital.
A Framework for Evaluating This Kind of Founder
When we brief boards or investors on a leadership search involving a founder-led retail or consumer business with an unconventional financing history, we push for three specific checks.
- Separate the financing mechanism from the underlying unit economics. Ask what each store or unit actually earned once open, independent of how its opening was funded. Ahammed's stores had to work on their own terms; the debentures only solved the timing problem of stocking them.
- Ask what trust was built before the business needed it. A founder's ability to raise unconventional capital is rarely spontaneous. It is usually the payoff of a much longer track record, worth understanding in its own right.
- Look at whether the model was formalized as it scaled. A workaround that stays informal caps out. One that gets professionalized, audited, and repeated at each new market, as Malabar's did across 14 countries, is a genuine operating capability.
Why This Belongs in the Boardroom, Not Just the Business Pages
This sits alongside the same category story we examined in C K Venkataraman's decade fixing how Tanishq read the Indian jewellery buyer: both leaders had to solve a problem specific to jewellery retail, capital intensity in Ahammed's case, customer trust in Venkataraman's, in ways that had no template to copy from outside the category.
The market does not reward the founder with the most conventional resume. It rewards boards and investors who can tell the difference between a workaround born of desperation and one born of genuine insight into what a business, and its customers, actually needed.
Sources
- Forbes India, How MP Ahammed built Malabar Gold & Diamonds: Small shop in Kerala to Rs 51,000 crore behemoth, August 2024
- India Ratings & Research, India Ratings Affirms Malabar Gold and Diamonds's Bank Loan Facilities at 'IND A+'/Stable; Rates New Limits, March 2026
- India Ratings & Research, India Ratings press release on Malabar Gold and Diamonds (FY26 provisional results), October 2026
- Malabar Gold & Diamonds, About Malabar Gold & Diamonds, accessed October 2026
- Gulf News, Malabar Gold & Diamonds continues rapid expansion, opens 300th global showroom in Dallas, USA, January 2023
- Gulf News, Louis Vuitton tops Global Powers of Luxury Goods 2023 List by Deloitte, Malabar Gold & Diamonds 19th, February 2024
- Economic Times, Malabar Gold to open 20 new showrooms by month-end at Rs 1,580 cr investment, March 2026
- ET Jewellery, Malabar Gold lines up Dubai push with three showroom openings before Diwali, October 2026
Related Reading
C K Venkataraman: How Tanishq Fixed Years of Being Wrong About India
Read → R · 02 Category Intelligence · August 2026Aukera Raised ₹90 Cr: Inside India's Lab-Grown Diamond Race
Read → R · 03 Compensation Data · June 2026The Hidden Comp Gap: Why Jewelry Brands Keep Losing Candidates at the Offer Stage
Read →Scaling a jewellery or retail brand and need leadership that has done it before?
We screen for candidates who understand the specific economics of jewellery and retail growth, not generalists borrowing a playbook from another category. Brief us on your next CXO mandate and we will tell you what the market actually has to offer.
Brief Us on a Mandate See all Sales & Retail roles we fill →